From AI Adoption to AI Execution
DIGITAL TRANSFORMATION

Author
Techurate Team
Publish Date
September 25, 2026
Last Update
September 25, 2026


From AI Adoption to AI Execution
There is an important difference between having AI and executing with AI.
A bank may have a chatbot answering customer questions, an AI model identifying potentially fraudulent transactions or a pilot supporting credit decisions. These are meaningful steps, but they do not necessarily transform how the institution operates.
AI execution begins when intelligence becomes embedded into everyday banking workflows.
An AI system that can securely access relevant customer information, interact with banking systems, follow defined policies, execute approved actions and escalate exceptions to employees represents a fundamentally different capability.
The question is therefore no longer simply where AI can be used.
It is about where AI can fundamentally improve the way banking is delivered and operated.
Five Barriers Between AI Pilots and Production
Data Is Everywhere, but Context Is Not
Banks have enormous amounts of data, but that data often exists across multiple systems.
Customer information may be distributed across core banking systems, CRM, lending, payments, fraud and other platforms. An AI system may have access to one source while lacking the context available in another.
Consider a customer asking about refinancing a loan.
An AI assistant may know the customer's account balance and payment history, but what if it cannot securely access other relevant information needed to support the interaction?
The result is familiar: the AI transfers the customer to a human, and the employee spends time gathering information from different systems.
The problem is not necessarily a lack of data.
It is the lack of connected, governed context.
For AI to create meaningful value, banks need ways to securely connect relevant data sources and make trusted information available at the right point in a workflow.
This does not necessarily require replacing existing systems. It requires creating the connections that allow them to work together.
Legacy Systems Need to Work With AI
Many banks operate on technology estates that have evolved over decades.
These systems remain critical to daily banking operations, but they were not necessarily designed for today's AI-driven, API-connected environment.
AI-enabled workflows may need to retrieve information from several systems, apply business rules, trigger actions, record decisions and maintain an audit trail.
That requires more than an intelligent model.
It requires an architecture that allows AI to interact with the broader banking ecosystem.
The practical answer for many institutions is not to replace everything.
It is to connect what already works with what comes next.
Modern APIs, integration layers, orchestration and composable architecture can allow banks to introduce new capabilities while continuing to leverage their existing core banking solutions and technology investments.
Governance Must Be Built Into AI
Banking requires a higher standard of accountability than many other industries.
When AI is involved in lending, fraud, compliance or financial operations, banks need to understand what information is being used, what actions the AI can perform and when human intervention is required.
As banks move from AI assistants toward agentic AI in banking, this becomes even more important.
An AI agent that can take action needs clearly defined permissions, policies, monitoring and escalation mechanisms.
This means governance cannot be treated as something added after deployment.
Governance needs to be part of the architecture from the beginning.
The objective is not to prevent AI from acting.
It is to create the conditions under which AI can act responsibly.
AI Must Solve Business Problems, Not Just Demonstrate Technology
Another barrier is organizational.
A technically impressive AI model can still fail to create business value if the people expected to use it do not see how it improves their work.
The starting point should therefore be the business problem.
Where are employees spending excessive time?
Which processes involve repetitive manual work?
Where are customers experiencing friction?
Where do errors, delays or operational costs occur?
These questions can lead to practical AI use cases in banking, such as:
Automating routine document processing
Accelerating customer onboarding
Supporting relationship managers
Improving fraud investigation
Assisting credit analysis
Streamlining internal operations
Providing employees with relevant information within their workflows
This is also where the idea of an AI workforce becomes important.
AI does not have to replace every human activity. It can take on appropriate repetitive and information-intensive tasks while employees focus on judgment, relationships and decisions that require human accountability.
AI Needs Measurable Business Outcomes
Eventually, every AI initiative faces the same question:
What did the investment deliver?
Model accuracy alone does not answer it.
Banks need to connect AI initiatives to measurable business outcomes.
For example:
Before AI
Customer onboarding takes several days
Employees perform multiple manual steps
Fraud investigators spend significant time reviewing cases
Staff search across multiple systems for customer information
After AI
Onboarding becomes faster
Manual work is reduced
Investigators receive prioritized cases
Employees receive relevant information within their workflow
The exact targets will vary by institution and use case.
What matters is establishing a baseline before implementation and measuring the change afterward.
Without that discipline, banks risk accumulating successful pilots without knowing which ones deserve to scale.
From AI Experiments to AI-Native Banking
Moving beyond pilots requires more than deploying individual AI models.
It requires a connected approach to architecture.
A practical transformation journey can begin with five steps.
Start With the Business Outcome
Identify a process where AI can create a measurable improvement.
Begin with the problem, not the technology.
Connect the Data
Identify the information required and establish secure, governed access across relevant systems.
AI needs context to be useful.
Connect AI to the Workflow
Move beyond generating answers.
Through APIs, orchestration and controlled actions, AI can become part of the actual banking process.
This is where AI begins moving from an assistant toward an operational capability.
Build Governance Into the Journey
Define permissions, policies, monitoring, auditability and human escalation before scaling.
Governance should not slow transformation down. Done correctly, it creates the framework that allows transformation to move forward with confidence.
Measure, Learn and Scale
Measure the business outcome.
Once a use case demonstrates value, banks can reuse the underlying integration, governance and architectural patterns for subsequent use cases.
This creates a compounding effect: every successful deployment can make the next one easier to implement.
The Next Banking Architecture Will Be AI-Native
Banking technology is entering a new phase.
Earlier digital transformation focused largely on putting existing products and processes online.
The next phase goes deeper.
AI can become part of how products are configured, services are delivered, decisions are supported and operations are executed.
This represents a shift from:
Digital banking → AI-enabled banking → AI-native banking
In an AI-native model, AI is not simply another interface placed on top of existing systems.
It becomes an intelligence and execution layer that can work across data, products, workflows and customer journeys within clearly defined governance boundaries.
This makes composability increasingly important.
Banks need the ability to introduce new capabilities without rebuilding their entire technology environment every time technology evolves.
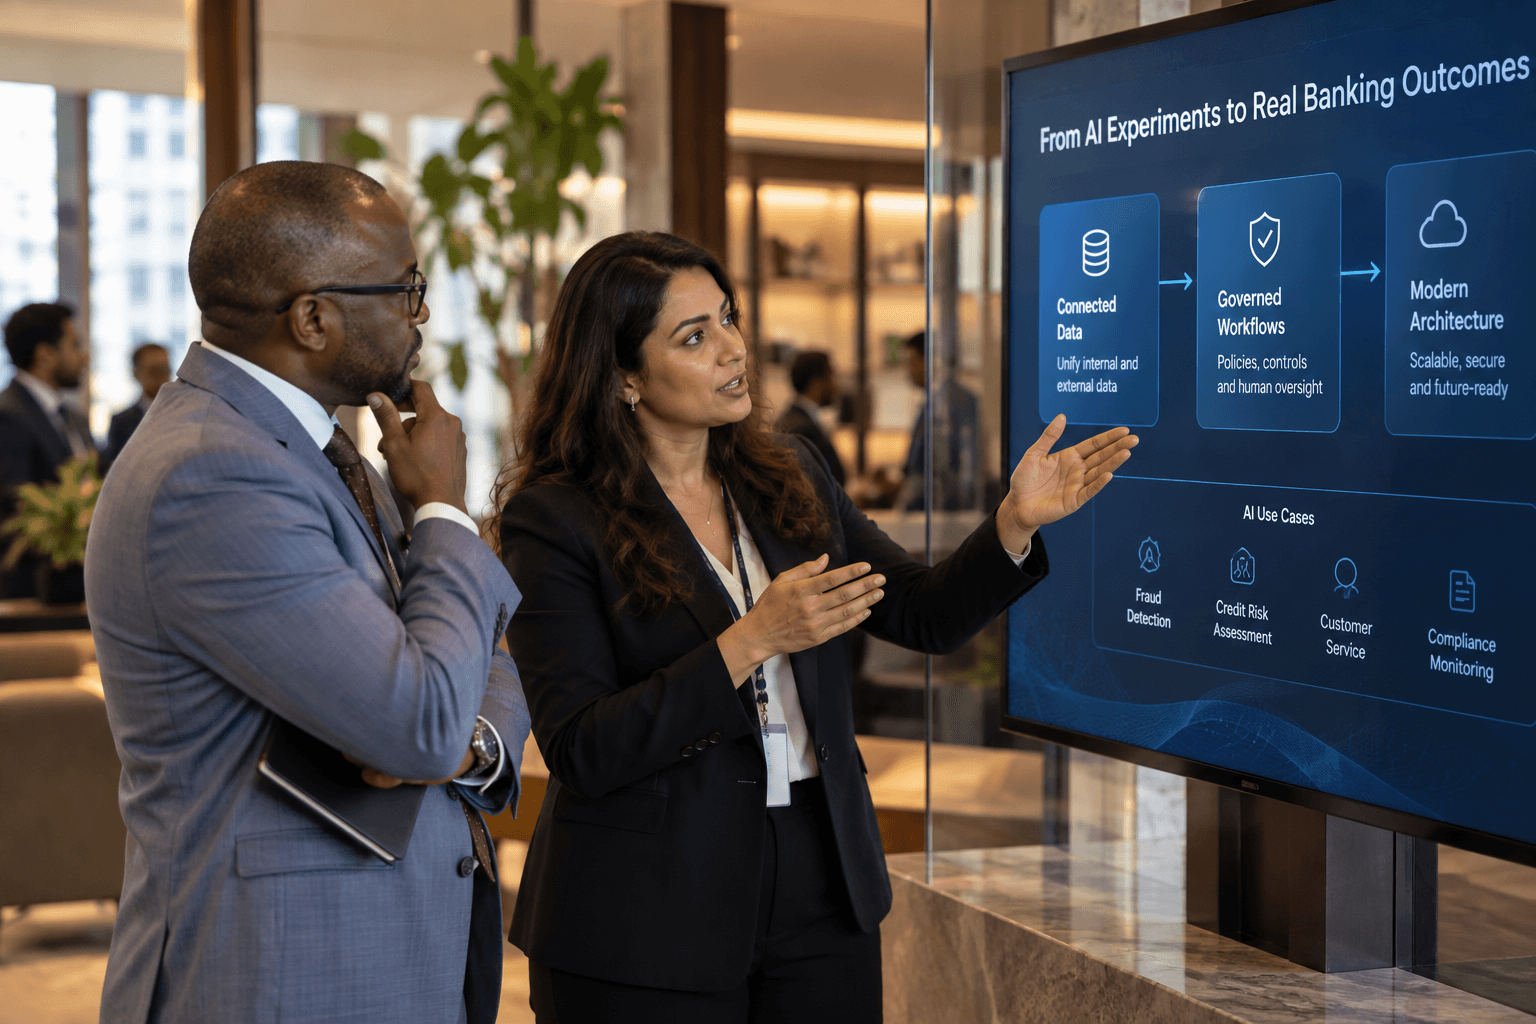
The emerging architecture brings together:
Data + APIs + Banking Systems + AI Models + Agents + Workflows + Governance
into a connected environment.
What This Means for Banks
The next competitive advantage in banking may not come simply from having access to the latest AI model.
Models will continue to evolve.
The differentiator will increasingly be how effectively a bank can put intelligence into action.
Can AI access trusted information?
Can it interact with existing systems?
Can it follow policies?
Can it execute approved actions?
Can employees work alongside it?
Can the bank measure the outcome?
And can the architecture support the next use case without starting from scratch?
These questions will determine whether AI remains a collection of experiments or becomes part of the bank's operating model.
From AI Experimentation to AI-Native Banking
The banking industry's AI journey is moving into a more demanding phase.
The first wave was about experimentation.
The next wave is about execution.
That means building the foundations that allow AI to operate across the institution — securely, intelligently and at scale.
The future of banking will not be defined simply by who experiments with AI first.
It will be defined by who can turn AI into a trusted, connected and measurable part of everyday banking.
Conclusion: From AI Pilots to AI-Native Banking
The real opportunity for banks is no longer simply to experiment with AI, but to make it work across the institution.
That requires more than powerful models. It requires connected data, modern integration, governed workflows and the ability to build on existing banking infrastructure.
When these foundations come together, AI can move from isolated pilots to supporting real customer journeys, employee workflows and banking operations.
This is the shift from AI adoption to AI execution and ultimately toward a more AI-native model of banking.

Read Blog
AGENTIC AI
Agentic AI in Banking: From Assistance to Intelligent Action
AI agents help banks understand goals, coordinate workflows, and act.
Published
August 31, 2026

Read Blog
CONVERSATIONAL BANKING
The Future of Banking Is Conversational
What comes after digital banking transformation, and why it matters now.
Published
June 23, 2026

Read Blog
AI BANKING
Financial Decisions Are Moving to AI
Why banks must move beyond transactions and become part of every financial decision.
Published
July 17, 2026